Risk protection is not a subject that most commercial cow-calf ranchers spend a lot of time considering. That’s not to say the typical rancher does not follow the markets or do their best to add value to their calves at sale time. Nevertheless, traditionally, the cow-calf rancher is a price taker and simply receives the price that the market dictates on sale day.
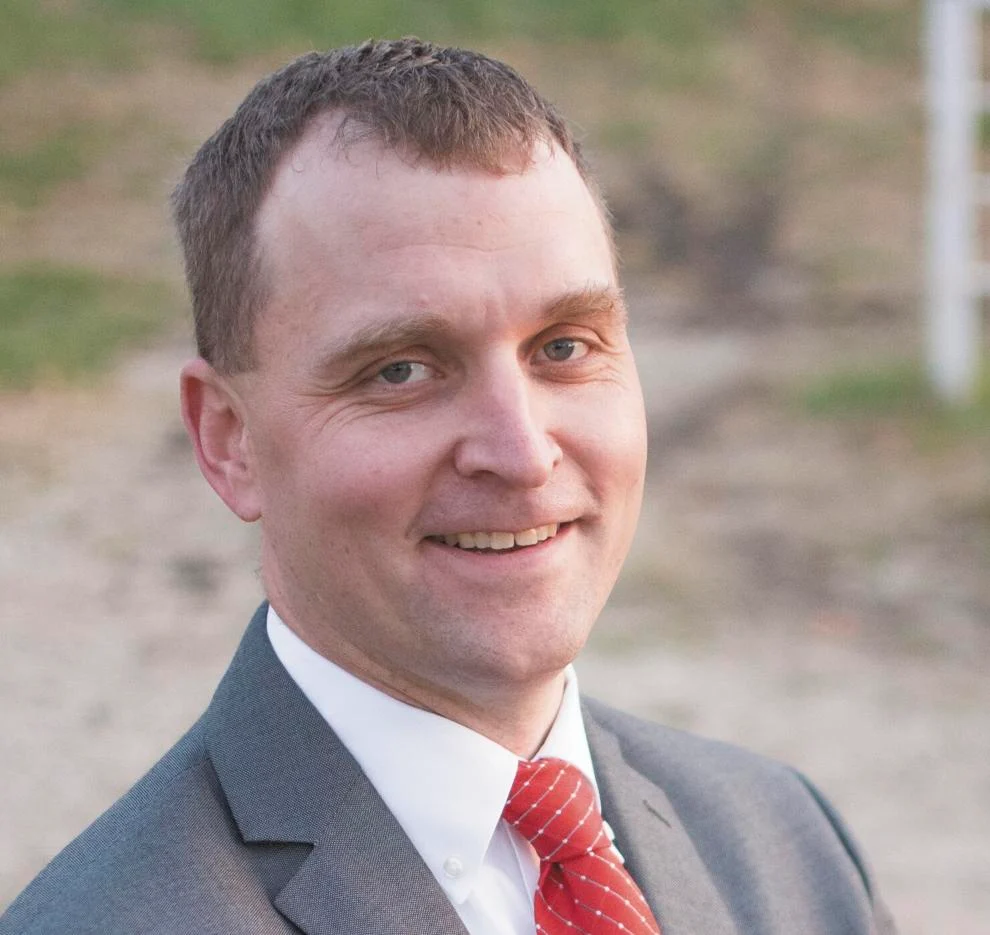
Until recently there has been no good option for price risk protection. However, USDA’s Livestock Risk Protection (LRP) program is just that, and Joe Kovanda of Compass Ag Solutions is working hard to spread the word and let ranchers know about their options with this program. He recently sat down with WLJ to share more information about this tool.
A native Montanan, Joe has focused his career on the cattle industry. He has worked for multiple large feedlots, helping them manage and analyze risk along with feeder cattle procurement. Before joining Compass Ag Solutions as their chief development and strategy officer he founded his own company, 4:10 Risk Strategies, helping producers in all segments of the cattle industry manage price risk.
LRP, in its simplest form, is price insurance for livestock. When asked to describe LRP, Joe said, “Imagine LRP as having another order buyer for your calves. This order buyer agrees to a price for a future delivery, even before the calves are born, if the seller desires. However, this order buyer will allow you to sell at a higher price if the market increases.”
Joe continued, “He simply sets a floor price on your calves. He will not penalize you if your calves come in heavy or even if you decide you want to background your steers and keep your heifer calves. You don’t have to sell the cattle to him. And if the market drops, this order buyer still pays you the agreed-upon price at the time of the contract no matter how much the market has dropped.”
There are some key factors to keep in mind when considering if LRP is a good option for you. First, LRP does not provide a cash down payment to the rancher at the time the contract is agreed upon. That happens at the LRP end date, or projected sale time. When determining what end date to choose for your LRP, you need to have an idea of when you will sell your calves.
If you sell on the “spot market,” which could look like your local auction market, you will choose an LRP end date as close to that projected sale date and anticipated weight. If you consign your calves to one of the many summer video sales, you want your LRP end date to be close to the date of that summer sale.
“It’s important to have the LRP end date align with your sale date,” Joe said. “If you sell your calves on a July video auction, you want to make sure the LRP ends near the same date in July as the sale. If you instead use an LRP end date close to the delivery date, the market can change in those months following the video sale and you leave yourself exposed to the risk of the fluctuation of the market.”
There is a 60-day window that you can ship your calves (dispose of title) before the LRP end date. So, if conditions get dry and you need to market your cattle early, you can do so 60 days before the LRP end date. Additionally, the soonest you can purchase LRP is 90 days out, so you can’t wait until three weeks before you sell to set a floor price with LRP.
What does this practically look like for price floors on 2024 spring-born/fall-shipped calves right now? The June through August 2024 LRP end dates used by cow-calf producers who sell on the summer videos are not offered yet. However, when they are offered in early September, Joe indicated they will equate to 575-pound steer calf floor prices at about $1,650/head, and 550-lb. heifer calves at about $1,480/head. That’s assuming the market doesn’t drop significantly into early September. This means that ranchers can begin to floor their 2024 calves at about those values in a few weeks.
LRP uses the CME Cash Feeder Cattle Index (FCI) to set the ending price of the LRP on the end date. The FCI is calculated each day and is publicly available. For different cattle weights and sexes, formulas are used to adjust the LRP settlement price, starting with the FCI as the base. Another key point is that LRP is not available for speculators. You must own the cattle that you purchase LRP for, and the head counts are paper audited to ensure that it is a producer-focused program.
There are multiple classes of cattle that can be covered through LRP. The first option available is unborn calves. A rancher can lock in a price protection floor on a set of calves before they are born. This class assumes a 50:50 heifer and steer ratio.
If the calves are born when you purchase LRP, there is a heifer class and a steer class available. A lightweight class of both steers and heifers allows for insurable weights up to 599 lbs./head. You can specify lower weights, such as 550 lbs. if that is your traditional marketing weight. A heavier-weight steer and heifer class can be used to insure heavier calves. The unborn class only allows you to insure weights up to 599 lbs.
“With unborn LRP, if your calves weigh 625 lbs. at shipping time, you will leave yourself exposed on the extra 26 lbs. but isn’t that better than having all 625 lbs. exposed?” Joe asked.
Moving through different examples, Joe discussed a rancher who had his unborn calves insured through LRP, both steers and heifers, but the rancher later decided to keep the heifers for replacements.
“The ‘LRP order buyer’ is OK with you keeping your heifers,” Joe said. “You simply let the LRP expire on its end date. At that time, you can purchase a new LRP floor at the larger weight class and price protect the heifers again.”
This option is designed for the yearling operators. After that contract expires, you could still insure the heifers one more time as fed cattle, if you retained ownership. On the replacement heifer side, after the heifers are exposed, they no longer qualify for the LRP program themselves, but the price of the unborn calves they are carrying is insurable.
Joe said, “In this example, you can provide price protection on your cattle at nearly every step of their development and production cycle. This provides ranchers with the opportunity to remove one more stressor and allows them more energy to focus on ways to improve the operation and factors within their control, like nutrition or genetics.”
There are many great opportunities provided through the LRP program. The process to enroll in the program is simple. It starts with a call to a licensed agent, like Joe, who helps you understand how LRP works and your available options. After that, there is a short application to complete and then you are eligible to purchase LRP coverage on your cattle.
It is important to note that once LRP is in place, it must be held until the end date. Though similar to a put option in function, you cannot sell out of the LRP coverage early like you could with a put option.
However, he noted, “Don’t let this discourage you. If you would like to pair LRP with other risk tools, like a put, there are ways to combine those tools to make LRP more flexible and to fit each individual.”
One of the best parts of LRP is that the LRP coverage cost is subsidized and the cost is not due until the end. The subsidy makes it cheaper than alternative price protection like put options.
“If the market goes up, which is what we all want and hope for, then your calves are worth more, and a bill for your LRP cost will be due after you have sold those cattle and have the cash flow from that sale in hand,” Joe said.
“If the market goes down and your calves are worth less, you will receive an indemnity check. The LRP cost will be subtracted from your check. The combination of the insurance check and the cattle sales will result in a total price, as if the market had not declined,” he continued.
Joe’s passion and knowledge about risk protection is evident when you talk with him. He really wants more ranchers who have not utilized risk protection to be aware of their options.
“We live in a 24-hour news cycle. There are things that affect the market that are completely out of our control. You can spend a lot of time worrying about the markets and the price you will receive for your cattle,” he said.
“If we can help take that worry away, this industry has even greater improvement potential. We have so much competition from competing proteins, meat alternatives and other food choices. We need to focus on continually improving the competitiveness of beef cattle.”
He continued, “If ranchers recapture the time they waste worrying about markets and refocus that time and energy on important factors within their control, the sky is the limit for competitive improvements in cattle and beef production. Helping cattle producers to be financially successful for decades to come is what drives me.”
You can find more information about Joe Kovanda and the Compass Team at Compass Ag Solution’s website, www.compassagsolutions.com. — WLJ