Cattle markets were strong in early February but have been challenged to absorb and digest a wide range of news. A few of the diverse issues are summarized below.
Inventory data
The Cattle report released in late January provides lots of data for market participants and analysts to digest over many days. The beef cow herd was down another 1%, extending the cattle cycle to at least a 12th year. A 0.9% increase in beef replacement heifers may indicate that the herd is stabilizing.
However, little or no growth in the cow herd is possible in 2026 and not much in 2027. Seven of the top 10 beef cow states saw a herd decrease in 2025 indicating that lingering drought and drought threats, along with financial challenges, continue to delay herd rebuilding.
Weather issues
A variety of weather concerns are part of the cattle market discussion. The drought map continues to deteriorate with growing concerns about the upcoming growing season.
The late January storms impacted beef cattle operations across a wide swath of the country and will have lingering impacts in the coming weeks. Storm impacts on feedlot cattle are likely to show up in carcass weights for a few weeks going forward. The delay in market-ready cattle has stimulated fed cattle markets into February. Some cow-calf producers were already calving during the storms, so longer term impacts on the calf crop are unknown at this time.
NWS and the Mexican border
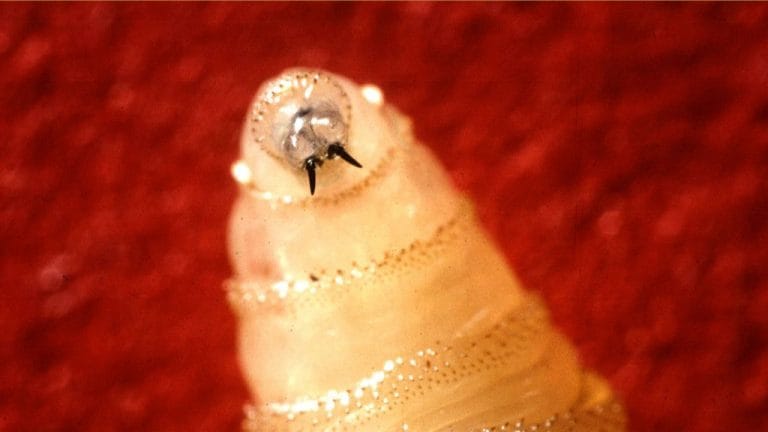
The cattle industry continues to nervously anticipate another shoe (or maybe two shoes) to fall in awaiting a reopening of the Mexican border and the continuing threat of NewWorld screwworm (NWS) arriving in the U.S. The market implications of both events are probably not as severe as the fear and uncertainty suggest, but both possibilities inject considerable potential volatility into cattle markets.
(Other) international trade
The latest release of monthly trade data catches up to the normal two-month delay with the release of data for November. For the first 11 months of last year, beef exports were down 13.8%, mostly the result of exports to China down 95.8% year over year for November and down 64.8% for the year to date. Beef imports through November were up 18.3%.
In early February, a presidential executive order increased the tariff rate quota for Argentina from 20,000 metric tons (mt) to 100,000 mt of beef. This could allow imports of Argentine beef to about double from 2025. Imports from Argentina were already exceeding the 20,000-ton limit. It’s not clear how much additional Argentine beef might actually be imported this year.
Argentina consumes nearly three-quarters of beef production domestically. Of the roughly 24% of beef exported, exports to the U.S. are only about 7% of Argentine beef exports. Increased exports of beef to the U.S. will compete with domestic demand in Argentina as well as exports to other markets. The impact in the U.S. is likely to be minimal.
Beef imports from Argentina would only be about 4% of U.S. imports if the new quota is filled and mostly likely an increase in imports from Argentina will simply displace imports from another country, not changing the total much, if any. — Derrell S. Peel, Oklahoma State University Extension livestock marketing specialist