Prior to the border closing in November 2024, U.S. imports of Mexican cattle had averaged 1.18 million head annually in the previous decade (Figure 1) and 1.12 million head per year in the previous 35 years. Mexican cattle imports equaled 3.4% of the total U.S. calf crop from 2015-24 and 3.1% since 1990. The brief border opening in 2025 allowed about 230,000 head to cross, 0.7% of the 2025 calf crop.

Figure 2 shows the average seasonal pattern of Mexican cattle imports from 2019-23. The typical pattern is bimodal with peaks in March and again in November/December. Calves carried over from the previous year are typically exported in the first half of the year with relatively few exported in the heat of the summer. New crop calves start to be exported in the final months of the year, carrying over into the next year. 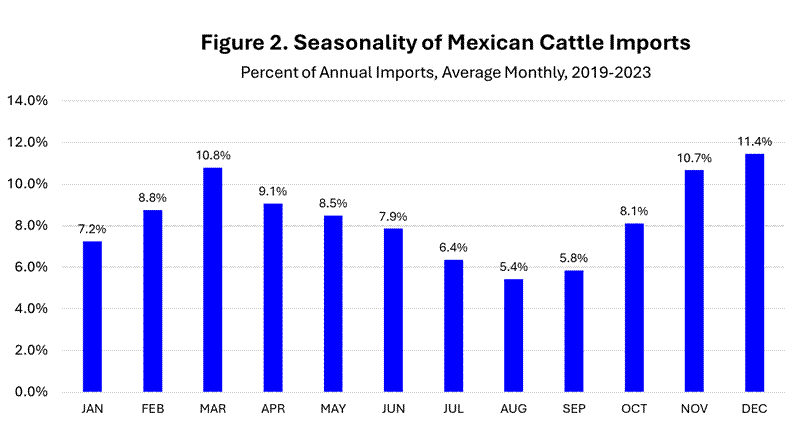
Figure 3 shows the distribution Mexican cattle imports by port in 2023, the last year with a fully open border. The largest port is Santa Teresa, NM, which accounted for nearly 43% of cattle crossing. Along with the Columbus port, New Mexico accounted for over 53% of total cattle imports. The ports at Nogales and Douglas in Arizona represented another 27.5% of cattle crossings. The six ports in Texas accounted for a total of 19.2% of total Mexican cattle imports. The largest Texas port is Presidio/Ojinaga with 7.7% of the total. 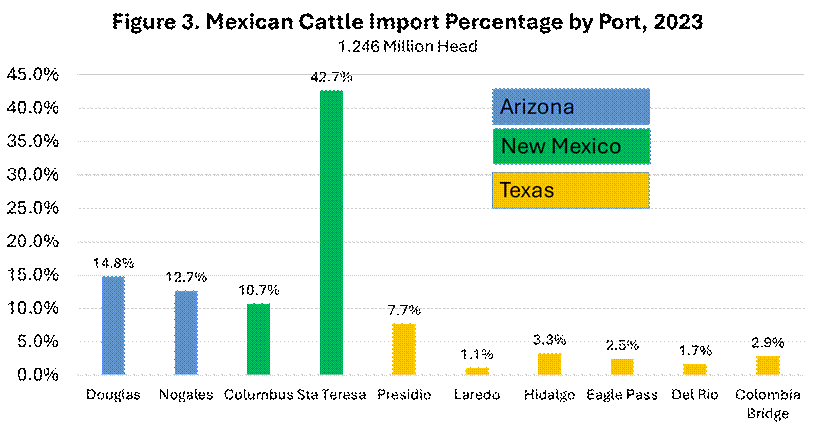
Rumors are currently swirling that the border could open soon, probably with the phased plan to open ports from west to east over time. How much and how fast can cattle imports recover? How fast is … not very. It will take several weeks for border facilities to restaff and have USDA personnel in place to inspect and clear paperwork for crossing cattle. It takes time (and cost) for Mexican producers to prepare cattle and the paperwork needed for crossing.
It’s not clear how aggressive Mexican producers will be initially until they have a sense of how stable the border situation might be. By the time that cattle can begin crossing it will be close to the heat of summer, which is likely to limit crossings. If it starts relatively soon, numbers of cattle imports could begin to recover significantly by fall.
Exactly what that recovery looks like, and the numbers expected, is uncertain. Mexico has continued to adapt since the border has been closed, utilizing previously exported cattle in domestic markets. Mexico has developed significant cattle feeding and packing infrastructure in the past 25 or so years.
More infrastructure investment is underway. Mexico is the eighth largest beef-producing country and the seventh largest beef-consuming country. Mexico is the No. 11 beef-exporting country and beef exports have grown more than 10 times in the past 20 years.
U.S. imports of Mexican cattle are part of an increasingly integrated cattle and beef trade relationship between Mexico and the U.S. Mexican cattle imports have been important for many decades. In the 1980s, Mexico became a significant beef export market for the U.S and is currently the No. 3 beef export market (Figure 4).

More recently, after 2010, Mexico has become a significant source of U.S. beef imports, currently the No. 4 source of beef imports (Figure 4). Cattle and beef trade between the U.S. and Mexico are interrelated markets so the current disruption in cattle movement across the border may have a variety of impacts in the future. — Derrell S. Peel, Oklahoma State University Extension livestock marketing specialist